Sunday, 31 May 2015

The Horror of the Confidence Fairy (part vi)

(From Part v)

"But the thing that is most needed now is something monetary policy can't directly cause: more of the sort of ‘animal spirits’ needed to support an expansion of the stock of existing assets." (Glenn Stevens, RBA Governor, here)
Lacking a theory of what causes slumps, Animal Spirits offer a convenient multipurpose explanation to the Keynesian economist: Animal Spirits strike unexpectedly, and create an exogenous, unpredictable shock to aggregate demand.

This is where Keynesian economists see themselves and the Government playing a role: they are there to counter, through fiscal and/or monetary policy, that shock.

With nuances and qualifications, many a Keynesian economist subscribes to the "Animal Spirits as imp who strikes once and is to be vanquished".
"But the goat, on which the lot fell to be the scapegoat, shall be presented alive before the Lord, to make an atonement with him, and to let him go for a scapegoat into the wilderness." (Leviticus 16:10. KJV)
Understandably so: it's convenient, neat and plausible.

----------
"There is always a well-known solution to every human problem -- neat, plausible, and wrong." (H.L. Mencken)
Other Keynesians -- particularly, Post Keynesians -- have taken issue with that view: it may be neat and plausible, but it's unfaithful to Keynes -- they argue -- therefore, it's wrong.

Again Ross Gittins, channelling the New Keynesians Akerloff and Shiller, gives a useful account of how Keynes' ideas were diluted and places the responsibility on Sir John R. Hicks' "efforts to make Keynesian thinking more acceptable to economists steeped in the neo-classical assumption" (here).

In Gittins' account, Hicks made the multiplier protagonist of Keynesian economics, leaving Animal Spirits out of the film, except for a cameo at the beginning of the story, "so they [Keynesian economists] could do what they thought mattered most, win support for Keynes's key policy prescription: the use of government spending to stimulate demand when it was deficient."

In what concerns Animal Spirits, that would have been Hicks' sin. In doing so, he created "the imp who strikes once and the avenging Keynesian economist" view.

Gittins' story seems more or less correct. Hicks, writing in "IS-LM: an Explanation":
"Neither of us [i.e. Keynes and himself] made any assumption about 'rational expectations'; expectations, in our models, were strictly exogenous. (Keynes made much more fuss over that than I did, but there is the same implication in my model also)."
So, perhaps Hicks did misinterpret or, at any event, misrepresent Keynes' ideas, particularly those regarding Animal Spirits/expectations: for Keynes -- the critics argue -- Animal Spirits played a much more central role.

They are probably right, as we've seen.

----------
"It will be admitted by the least charitable reader that the entertainment value of Mr. Keynes' General Theory of Employment is considerably enhanced by its satiric aspect." (Sir John Hicks, "Mr. Keynes and the 'Classics' ")
Before casting the first stone, however, put yourself in Sir John's shoes.

How would you have explicitly modelled the effect of "digestion", the "weather", "fear", "nerves", and "hysteria" on the decisions of the "average business man" (let alone convinced your readership that you were actually being serious)?

Would you have made a deliberate fuss over that?

And how would you have explicitly modelled the effects of activist policy on "the fear of a Labour Government or a New Deal" on the investment decisions of the "average business man"?

Keynes' Animal Spirits may work reasonably well as a self-referential joke, but, as Sir John may have understood, economic theoreticians are known for their dull sense of humour.


Friday, 29 May 2015

Kooks, Krusaders and …


"By the early 1930s, Keynes and his followers felt a sense of urgency, almost of desperation, to get their ideas accepted. It became the hallmark of Keynes's coterie to regard every economist outside Cambridge as mad or stupid (…) The Keynesian position -- and this partly included Keynes -- was much more peremptory: error must be extirpated to prevent catastrophe." (Robert Skidelsky, here).

French Christians extirpating Jews. [A]
Sometimes respondents to blog posts add valuable insight, consciously or not, to the posts they comment on.

Take, for instance, this guy's comments (let's call him X) to a recent post in Mark Thoma's blog (for obvious reasons, I will not post the relevant links).

Before proceeding, let me be clear about my opinion on X: he seems to be intelligent, articulate, and educated; he is a believer in some kind of Keynesian economics; he is passionate, and probably sincere in his leftish beliefs (including his gut-level hatred towards Marxism and Marxists); the other side of that passion/sincerity coin is X's intolerance and zealotry -- extending well beyond Marxism -- which make him very vocal.

Readers, even if they have never crossed paths with X, may know the type (here is my fictional Klose Encounter of the Third Kind with one such character).

Thoma's original post appeared at 12:24 AM (his local time), a few days ago. Including title and date, it contains exactly 250 words, mostly from a long quote to an external article by another author. As is well-known, Thoma not only writes his own posts, but also refers his readers to others' writings. X's contributions were added to one such post.

X's first comment appeared at 05:02 AM; his last, at 02:58 PM, the same day: X devoted, at least partially, eight hours to evangelising the heathens.

The table below sums up the reaction that post generated (as of May 24, 07:59AM, AEST) and X's part of it and suggest a measure of X's personal involvement:

       Comments    %   |  Words    %
-------------------------------------
X          14      11  |  2,632    30
Total     126     100  |  8,945   100

Note: "Words" include automatically generated text: time
stamp, headings (A "said in reply to" B).

X's response alone represented 11 times Thoma's literary stimulus (250 words). That's what I call a Keynesian multiplier!

Beyond the funny side, that's telling, isn't it?

----------

X's case offers insight in a deeper sense.

Prompted by a comment, in one of his interventions (an 802-word long comment that could qualify as a blog post in its own right) X offers a good summary of Keynes' thought and some of the reasons why "Austerians" oppose it.

He starts:
"Let's not be naive about all this. Conservatives regarded Keynesian economics as a socialist Trojan horse being wheeled into the academy by the reds in Cambridge, England (…) And the rich and privileged saw Keynesian economics as a direct attack on their personal bank accounts."
Then, X gives a brief but intelligent overview of Keynes' argument, at least as seen by X. For brevity's sake, I'll omit it here entirely.

X (remember: himself a leftist of sorts) adds:
"Keynes was rhetorically deft at softening the blow of his radical proposals by considering them as a more conservative alternative to full-blown socialism".
After a long quote from the Master, X concludes:
"Because the global context in which Keynes was writing was one in which there was a politically powerful state socialist alternative to his left, Keynes was able to present his more moderately semi-socialist position as 'moderately conservative'. But of course, this rhetoric was not likely to be compelling to the banking and financial class, the rentier class and other high-flying capitalist entrepreneurs and industrial barons (…)."
It's not the first time I hear that. Frankly, I didn't buy it then, and I don't buy it now. But, for the sake of the argument, let's assume X's views: Keynes was selling his actually "semi-socialist position" as "moderately conservative" to "the rich and privileged" to cajole them into the Diet Coke of socialism.

Can you blame "the rich and privileged" for rejecting Keynes' position?

I, however, suspect X -- giving him the benefit of the doubt -- is innocently selling Keynes' actually "semi-conservative" position as "moderately socialist" to the working people, to cajole us into accepting something capitalists did not (and never will) accept: at best, futile, at worst, suicidal.

Can you blame us for rejecting Keynes' position?

And that's the thing with X: in his argument there is no reference whatsoever to the invisible working people; apparently he assumes we must accept his Revelation -- actually, his version of his Lord's Gospel -- in blind faith. When we don't, his wrath and that of the Lord befalls upon us.


(From Verdi's "Messa da Requiem", conductor Claudio Vandelli, New Russia State Symphony Orchestra)

----------

To put X in perspective. He may be annoying, fanatical, and ultimately irrational, but at least he is literate. How much worse are those who pontificate with the same feverish zeal, but with no knowledge?

Incidentally, now it's Prof. David Ruccio's turn to endure one such missionary. Looking at the bright side, at least one thing is appropriate: this person's nom-de-guerre is CardiffKook.

Priceless! See now how you can gain insight from your commenters?


Update:
31/05/2015. Added the video.

Image Credits:
[A] "French Jews are being executed by burning" (c. 1410). Author: Unknown. This image is in the public domain. Source: Wikipedia.

Tuesday, 26 May 2015

The Horror of the Confidence Fairy (part v)

(From part iv)

(source)

"
[I]t was Keynes, not Marx, who cracked the code of crisis economics and explained how recessions and depressions can happen." (Paul Krugman, "Why Aren't We All Keynesians Yet?")
"A good way to understand the origins of the current economic crisis in Australia is to examine the historical behaviour of key macroeconomic aggregates." (Bill Mitchell, "The Origins of the Economic Crisis")
"Q: So uncertainty is the root cause of this unemployment equilibrium?
"A: No uncertainty is NOT central for unemployment. Lack of demand is, even if prices are flexible. (Matías Vernengo, "History versus Equilibrium: a False Dichotomy")
"Animal spirits -- also known as 'confidence' and 'expectations' -- are the main factor causing the economy to speed up and slow down, speed up and slow down again". (Ross Gittins, "Economy Follows Wherever our Moods Take us")
"It will not do to treat questions relating to economic policy, to trade and industry, and especially to population, as if they were metaphysical speculations in which each person can adopt the point of view which appeals most to his temperament -- and still more frequently, perhaps, to his private interests." (Knut Wicksell, here)

One thing is to figure out who the Confidence Fairy's estranged deadbeat dad is, another is to determine how much unpaid child support he owes her mother.

But here we shall not attempt that. Instead, let's try to understand how Animal Spirits explain recessions.

Things are bound to get interesting.

----------

Given the previous selection of opposing opinions, something must be clear: if Keynes "cracked the code of crisis economics and explained how recessions and depressions can happen," he took the secret to the grave.

From Mitchell's current non-Keynesian disregard for Animal Spirits (which I, for what it might be worth, applaud and share), to Vernengo's somewhat middle-of-the-road position, to Gittins' all-powerful Animal Spirits, there is an ample range of colours, sizes, and models to choose from.

(Bear with me on Gittins' inclusion in the list:  his position, influenced by the work of George Akerlof and Robert Shiller, is not all that different from Lord Skidelsky's and it can be contrasted with Keynes' own).

Paul Krugman's own stance seems closer to Vernengo's.

----------

(source)

After crafting the separate threads of his argument (Chapter 12 explaining Animal Spirits), Keynes weaves them in Chapter 18. His model has "given factors", independent variables and "volume of employment and the national income", as dependent variables.

After some preliminary considerations, Keynes: "Thus we can sometimes regard our ultimate independent variables as consisting of 
  1. the three fundamental psychological factors, namely, the psychological propensity to consume, the psychological attitude to liquidity and the psychological expectation of future yield from capital-assets
  2. the wage-unit (…) and 
  3. the quantity of money (…)"
A comparison between Keynes' uncertain attempts at psychologising -- at least as reflected in Chapter 12 and reinforced in the passage above -- and the thought of his contemporary followers would seem to indicate that Gittins' Keynesian interpretation (and Skidelsky's before his retraction) is the closer match!

Would that qualify as "metaphysical speculations"?

----------

Upon closer inspection, readers will note that Mitchell (a Post Keynesian economist strongly influenced by Marx) is explaining his own practice with no explicit reference to Keynes, let alone his Animal Spirits. A few years ago, he would still mention it -- with already palpable ambivalence. My guess is that experience has made Mitchell gradually drift away from the Master, at least on that: he, unlike Keynes, exclusively considers objective, measurable variables.

To the extent that quote is representative (and it may not be), Vernengo's position seems more ambiguous. Himself a Post Keynesian influenced both by Marx and Sraffa, one could expect his views on Animal Spirits to be closer to Mitchell's than to Gittins'. In fact, in that quote it's unclear whether he is explaining his own views, or those of Keynes (if the latter, I'm afraid he doesn't seem to be right).

----------

So, Prof. Krugman, Keynesian views on the cause of the current situation seem to run the whole gamut, from the materialist, to the extremely subjectivist -- or metaphysical, if you will. Not bad, for the "explanation" Keynes decoded.

Somehow, I'm reminded of Nikolai Bukharin: "[T]he motives of the isolated individual constitute the point of departure for the Austrian School".


Image Credits:
I found those images on the internet. If readers know for a fact I am infringing anyone's property rights, please leave a comment and, at your discretion, I will either remove the image or provide full credits.

Sunday, 24 May 2015

Bits and Pieces (VI)


Without mentioning her by name, Keynesian economist Paul Krugman ("Conservatives and Keynes", May 5, 2015) writes on the Confidence Fairy.

In my opinion, whether he realises it or not, this is the key part of his post:
"Keynesian economics, if true, would mean that governments [and economists, I'd add] don't have to be deeply concerned about business confidence, and don't have to respond to recessions by slashing social programs."
However, can you write "Keynesian economics" without "Animal Spirits"?

----------

One who would probably deny that is Prof. Roger Farmer (Distinguished Professor of Economics, at UCLA, apparently a non-Post Keynesian economist): he proposes the adoption of Animal Spirits as a new fundamental for Keynesian economics.

In a post ("Rational Expectations and Animal Spirits", February 3, 2014) last year, Farmer had this to say about his work:
"In standard dynamic stochastic general equilibrium (DSGE) models there is a single rational expectations equilibrium. In the models I work with there are many rational expectations equilibria. Not just one, or two or three: but an infinite dimensional continuum of them. That is not a problem. It is an opportunity that I exploit to model the idea that beliefs matter. In my work, I close my models by adding an equation that I call a 'belief function'. The belief function is an effective way of operationalizing the Old Keynesian assumption of 'animal spirits'. It is a forecasting rule that explains how people use current information to predict the future. That rule replaces the classical  assumption that the quantity of labor demanded is always equal to the quantity of labor supplied."
Now (and this is the thing), how would that fit with Keynes' -- the oldest Keynesian -- Animal Spirits, is something I cannot fathom. To paraphrase Him (about whose words I was reminded recently): "I simply do not know".

----------

Incidentally, Paul Krugman alludes to Farmer in "Choose Your Heterodoxy" (25-04-2015). An appropriate title, no doubt. But that's not why I draw your attention to it. What caught my eye is this:
"As I've written many times, economists who knew their Hicks have actually done extremely well at predicting the effects of monetary and fiscal policy since the 2008 crisis, whereas those who sneered at this old-fashioned stuff have been wrong about almost everything."
So, economists -- at least those who "know their Hicks" -- can predict things extremely well.

Fair enough. One is entitled to bragging rights if one makes a prediction and it comes to pass. Why should that be interesting?

Well, because other Keynesian economists (like Wren-Lewis and Syll) say economic prediction is not possible. In fact, neoclassical Marxist Chris Dillow agrees with them on that:
"Macroeconomics - when done well, which is only some of the time - does the former [explanation]. This might be all that can be expected. Whatever else is wrong with macro theory, the inability to foresee recessions is not the problem." 
----------

Is that just me, or these are strange times?

----------

UPDATE:

(source)

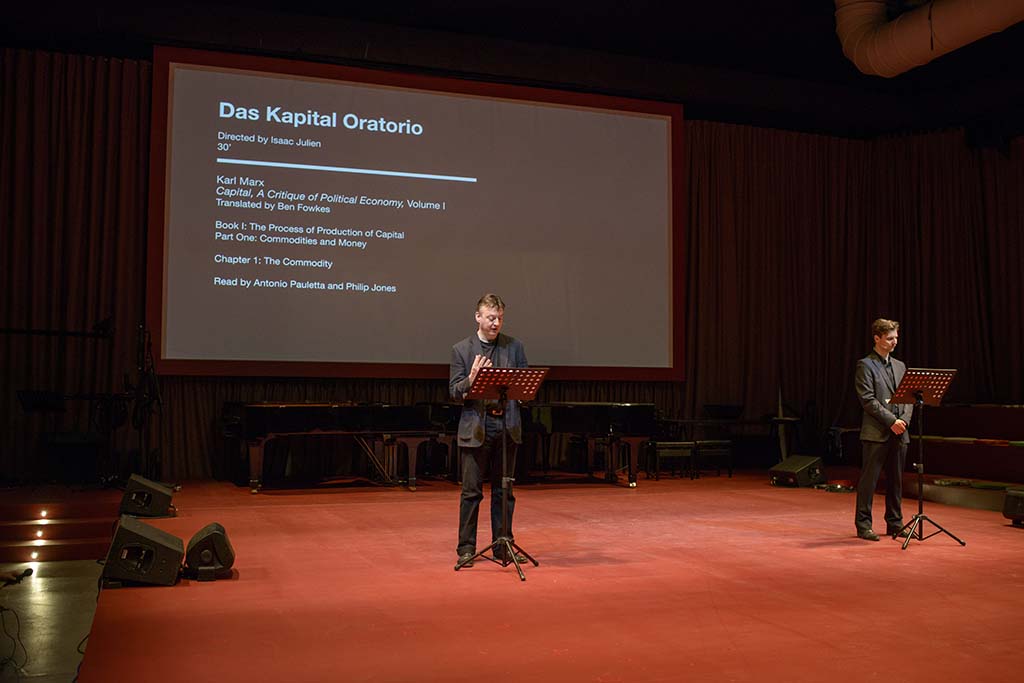
I couldn't hope for a better way to illustrate my previous comment on the strangeness of our times than pointing to "Das Kapital at the Arsenale: how Okwui Enwezor Invited Marx to the Biennale", by Charlotte Higgins (h/t David Ruccio), on the public readings of Das Kapital in the Venice Biennale.